What Is Short-Term Capital Gain (STCG) Tax on Shares? The 20% Rate, Section Rules, and Set-Off Mechanics

 Author
 Editor
STCG, or Short-Term Capital Gains, is the profit you make when you sell listed shares within 12 months of its purchase. STCG tax is currently 20% with no exemption limit of exceeding ₹1.25 lakh in a financial year.
But the 20% rate is not the whole story. Surcharge, cess, capital losses, and your total income can also affect your final tax. So, how much LTCG tax do you actually pay? Let’s understand the rules with simple examples.
What Is Short Term Capital Gain Tax on Shares?
Short Term Capital Gain (STCG) tax is a tax that you pay on a gain you have made by selling the stock within 12 months from its purchase.
Is Intraday Trading Short Term Capital Gain?
No, as per Indian tax law, intraday trading is not classified as a STCG (short-term capital gain), instead it is classified as speculative business income under Section 43(5) of the Income Tax Act , because in intraday trading, we buy and sell the shares on the same day without any actual delivery.
Since STCG only applies on holding of shares for less than 12 months, intraday trading can not be classified as STCG. The table below shows the typical tax classification for different trading types.
| Activity | Typical tax classification |
| Equity delivery investment sold within 12 months | STCG |
| Equity delivery investment sold after 12 months | LTCG |
| Equity intraday | Speculative business income |
| F&O trading | Non-speculative business income |
| BTST | Depends on whether activity is treated as investment or trading |
The profits from intraday trading are added to your total income and taxed at your applicable income tax slab rate.
How Are F&O and BTST Profits Taxed?
F&O trading is taxed as non-speculative business income under Section 43(5), whereas tax on BTST (Buy Today Sell Tomorrow) depends whether the shares are held as an investment or as stock-in-trade.
- Tax on F&O: As F&O contracts are derivatives contracts not the actual sharers, they get settled on exchange without delivery. Since there is no delivery of shares during settlement, F&O trading is taxed as non-speculative business income.
- Tax on BTST (Buy Today, Sell Tomorrow): BTST is generally taxed as STCG because you bought the shares to take delivery, but you sold them before they got settled and you also paid STT on both sides (during and selling).
However, there is a gray area, if you do BTST frequently and systematically as your main trading style, the tax department will actually consider it a speculative/business income rather than genuine capital gains.
What Is the STCG Rate on Shares Right Now?
As of 2026, the STCG tax rate on listed equity shares is 20% which only applies when you sell your holdings in profit within 12 months from the date of purchase. Unlike LTCG (Long Term Capital Gain) tax, where you get a ₹1.25 lakhs exemption, STCG tax has no exemption threshold and you will be taxed 20% on your entire profit.
For instance, you have sold your investment for a profit of ₹2 lakh. Let’s discuss how this profit will be taxed if it was short-term gain or long-term gain.
| Particulars | STCG | LTCG |
| Capital gain | ₹2,00,000 | ₹2,00,000 |
| ₹1.25 lakh exemption | Not available | ₹1,25,000 |
| Taxable gain | ₹2,00,000 | ₹75,000 |
| Applicable tax rate | 20% | 12.5% |
| Tax before cess | ₹40,000 | ₹9,375 |
| 4% Health & Education Cess | ₹1,600 | ₹375 |
| Total tax | ₹41,600 | ₹9,750 |
As you can see, we got taxed for the entire ₹2 lakh profit when it was gained within 12 months of purchase.
When Is a Short-Term Gain Taxed at Slab Instead of 20%?
When the short-term gain comes from selling unlisted shares that do not fall under section 111A, the gains are generally added to your total income and taxed at the applicable income-tax slab rate.
How Do You Calculate STCG on Shares?
You can calculate STCG tax by following three simple steps. The steps involve finding a STCG (short term capital gain), then subtracting eligible transfer expenses, and applying the applicable tax rate.
Let’s calculate the STCG tax for one of our successful trades in Vedanta Limited shares.
Step 1: Calculate the STCG (Short Term Capital Gain)
We bought the 1000 shares of Vedanta Limited stock on 15 Dec 2025 at ₹215 after the stock broke its all time high.
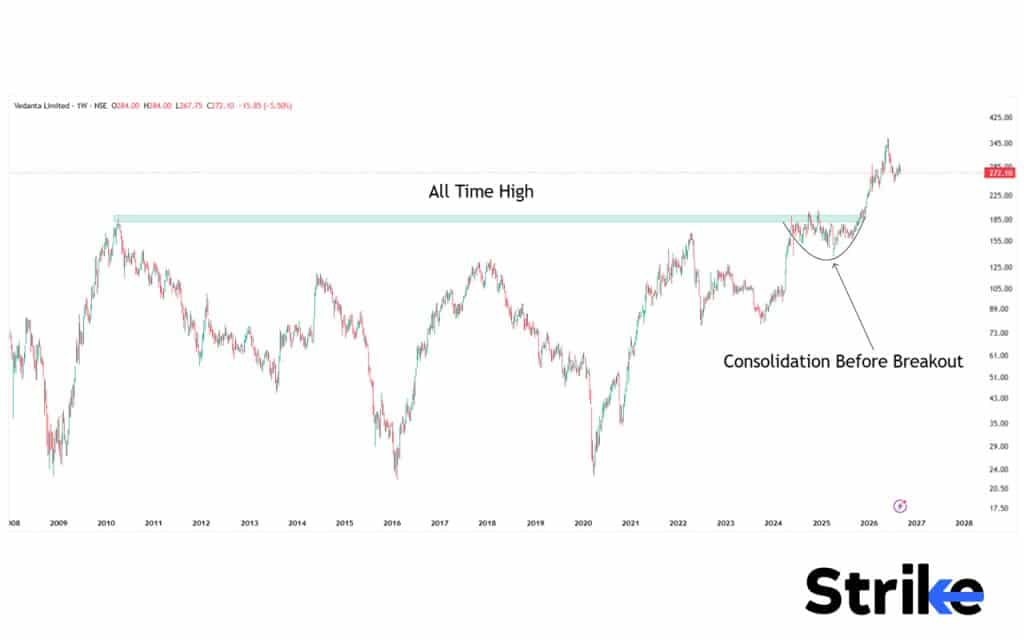
We held the position till 119 days and exited at ₹296 on 13 April 2026, with almost a 35% return. So our total STCG (Short Term Capital Gain) can be calculated as.
- Buying cost = 1,000 shares × ₹215 = ₹2,15,000
- Selling cost = 1,000 shares × ₹296 = ₹2,96,000
- Gross profit: Selling cost – Buying cost = ₹81,000
Since we have gained ₹81,000 in 119 days, we are eligible for paying STCG tax.
Step 2: Calculating Eligible Transfer Expense.
We have taken this trade through Zerodha broker, so we will calculate the transfer expense accordingly.
| Charge | Amount |
| Brokerage | ₹0 |
| STT (0.1% buy + 0.1% sell) | ₹511.00 |
| Exchange transaction charge (NSE) | ₹16.45 |
| SEBI charges | ₹0.51 |
| GST (on brokerage + SEBI + txn) | ₹3.05 |
| Stamp duty (buy side) | ₹32.25 |
| DP charge (on sell) | ₹15.93 |
| Total charges | ≈ ₹579.19 |
Note that, DP charges vary across brokers between ₹15 – ₹20.
Step 3: STCG Tax Calculation.
Since STT was paid and shares were held under 12 months, gains fall under Section 111A (now Section 196) at flat 20%. Note that the STT is not considered while calculating the STCG tax.
Taxable gain = STCG – Trading Cost (without STT) = ₹81,000 − ₹68 = ₹80,932
20% of Taxable Gain = ₹16,186
Hence we have paid ₹16,186 STCG tax on profit of ₹81,000. After STCG tax a 4% cess also applies on your taxed amount. This makes your total tax of ₹16,844.67.
Note: STT paid cannot be added to cost of acquisition or deducted from sale value for this calculation — the tax is computed on the plain gross gain.
- Short-term capital gain = ₹81,000
- Tax @ 20% = ₹16,200
- 4% Health & Education cess = ₹648
- Total STCG tax ≈ ₹16,848
(This excludes surcharge, which only kicks in if your total income crosses ₹50 lakh+ — surcharge slabs apply on top if relevant to you.)
Net summary
| Item | Amount |
| Gross profit | ₹81,000 |
| Less: Zerodha charges | ₹563 |
| Less: STCG tax (20% + cess) | ₹16,848 |
| Net take-home profit | ≈ ₹63,589 |
So out of your ₹81,000 gross gain, you’d effectively keep around ₹63,600, with taxes being by far the bigger bite compared to Zerodha’s near-zero delivery charges.
Is There Any Exemption on Short-Term Gains?
No, there is no exemption in short-term gains. Unlike LTCG (Long Term Capital Gain) tax, where you get a ₹1.25 lakhs exemption, STCG tax has no exemption threshold and you will be taxed 20% on your entire profit.
However, certain other provisions can affect the amount of tax payable, including the basic exemption limit available in specific cases.
Can You Use Your Basic Exemption Limit Against STCG?
Yes, you can use your basic exemption limit against LTCG but only under specific circumstances. Let me explain how.
If your basic income such as salary, business income, interest, etc is less than your basic exemption limit, which is typically ₹4 lakh under the new tax regime and ₹2,50,000 under the old tax regime, you can use the remaining exemption limit against your LTCG apart from ₹1.25 lakh.
Suppose your basic exemption limit is ₹4 lakh and your salary and other income is ₹3 lakh, your unused basic exemption limit becomes ₹1 lakh. Now you can use this ₹1 lakh exemption limit against your STCG to reduce tax.
So, if your STCG is ₹2 lakh, you can use your ₹1 lakh exemption limit after which the tax 20% will be only applied to the remaining ₹1 lakh profit.
How Do You Set Off Short-Term Capital Losses?
Under section 70, 71, and 74 of the Income Tax Act, STCL (short term capital loss) can be used to set off against both STCG and LTCG. This makes STCL more flexible compared to LTCL (long term capital gain) which you can use only to set off LTCG.
Suppose, I have a STCL of ₹2 lakh, here is how I will use it to set off my STCG and LTCG.
- STCL: ₹2,00,000
- STCG: ₹80,000
- LTCG: ₹1,50,000
Since a Short-Term Capital Loss (STCL) can be used to offset both STCG and LTCG, here’s how the calculation works.
Step 1: Offset the STCG first
| Particulars | Amount |
| Short-Term Capital Loss (STCL) | ₹2,00,000 |
| Short-Term Capital Gain (STCG) | ₹80,000 |
| STCL used to offset STCG | ₹80,000 |
| Taxable STCG | ₹0 |
| Remaining STCL | ₹1,20,000 |
Step 2: Use the remaining loss against LTCG
| Particulars | Amount |
| Long-Term Capital Gain (LTCG) | ₹1,50,000 |
| Remaining STCL available | ₹1,20,000 |
| STCL used to offset LTCG | ₹1,20,000 |
| Remaining LTCG | ₹30,000 |
In case, your STCL is more than your gains, you won’t be able to use or adjust your entire loss in the same year. During such a situation, you can carry forward your remaining losses to set off STCG and LTCG next year. However, you can only carry forward your remaining losses up to 8 years.
Why Is the Surcharge Cap an Advantage for High Earners?
For normal income such as salary, business income, etc, the surcharge can go up to 25% or 37% under the applicable regime. However, for capital gain, whether STCG or LTCG, the surcharge is capped at 15% under Section 111A for STCG and Section 112A for LTCG.
Suppose your total income is ₹6 crore, out of which ₹2 crore comes from STCG. If we don’t consider the 15% cap of surcharge on STCG, we will have to pay the highest surcharge rate of 37% under the old regime.
- STCG tax = 20% of ₹2 crore = ₹40 lakh
- Surcharge on STCG Tax at 37% = ₹14.8 lakh
- Total = ₹54.8 lakh
However, with the 15% cap
- Tax on STCG = ₹40,00,000
- Surcharge capped at 15% = ₹6,00,000
- Total = ₹46,00,000
As you can see, we have saved ₹8.8 lakh just because the surcharge rate is capped at 15% for STCG.
Which Act and Section Applies Now on STCG?
For income earned up to 31 March, 2026, section 111A of the Income Tax Act, 1961 applies. Whereas on income earned after 31 March, 2026, Section 197 of new Income Tax Act, 2025 apple.
| Particulars | Old Law | New Law |
| Act | Income-tax Act, 1961 | Income Tax Act, 2025 |
| Section for STCG (Equity) | Section 111A | Section 197 |
| Applicable for | Income up to 31 March 2026 (AY 2026–27 and earlier) | Income from 1 April 2026 onwards |
| Effective Date | — | 1 April 2026 |
Although the Act and sections have changed, the core principle remains the same. Only the section number and the surrounding structure has been changed.
When Do You Pay, and Where Does It Go in Your Return?
You pay STCG tax only when you sell your holdings and actually realize a profit. Until you sell them, any increase in their value is considered an unrealized gain, or simply profit on paper.
Suppose you sell your stocks on 15 March 2026. This means the sale happened during FY 2025–26. The income from that sale will be reported in your Income Tax Return for FY 2025–26, which is generally filed in AY 2026–27.
Now, there are two different mechanisms through which you may pay your STCG tax: Advance Tax and Self-Assessment Tax.
- Advance Tax: If your total estimated tax liability for the financial year, after considering TDS and other eligible tax credits, exceeds ₹10,000, you may be required to pay tax in advance during the financial year instead of waiting until you file your ITR. Advance tax is generally paid in installments.
- Self-Assessment Tax: This is any remaining tax that you pay yourself after calculating your final tax liability while preparing your ITR. For example, if you have not paid enough tax through advance tax or TDS, you need to pay the remaining amount as self-assessment tax before filing your return.
How Do You Reduce STCG on Shares Legally?
There are five different ways to reduce the STCG tax on shares legally which are briefly discussed below.
- Tax-Loss Harvesting: Sell the losing stock white booking profit. This will reduce your taxable net profit and eventually the STCG tax. If you have ₹2,00,000 STCG and ₹80,000 STCL and you sell them simultaneously, your taxable income becomes ₹1 lakh instead of ₹2 lakh.
- Use Your Unutilized Basic Exemption Limit: If your regular income (salary, interest, etc) is less than the basic exemption limit (₹2.5L old regime / ₹4L new regime), you can exceed the remaining exemption limit against STCG tax.
- Convert it to LTCG: If your stock is reaching 12 months and you don’t need money urgently, wait and convert the STCG to LTCG to get 12.5% tax along with ₹1.25 lakhs exemption limit.
- Consider an HUF Structure (If Applicable): If you have a Hindu Undivided Family entity, it gets its own separate basic exemption limit and tax slabs, independent of your individual filing. Transferring some equity holdings to the HUF (subject to proper legal process) can effectively double up on exemption limits across the family unit. However, this needs proper documentation and is best done with a CA/lawyer, since improper HUF fund transfers can be challenged.
- Carry Forward Losses From Previous Years: If you have unused STCL, you can carry it forward for 8 years and use that loss to set off the future gains.
Hence, you don’t reduce STCG tax by hiding. You do it by using your STCL or remaining personal exemption limit.
STCG, LTCG or Business Income — Which Applies to You?
Whether STCG, LTCG or business income applies totally depends on how you trade or invest and how long you hold your shares.
| Type of Income | When Does It Apply? | Tax Rate |
| STCG (Short-Term Capital Gain) | You buy listed equity shares and sell them within 12 months. | 20% (plus applicable surcharge and cess) |
| LTCG (Long-Term Capital Gain) | You buy listed equity shares and hold them for more than 12 months. | 12.5% on gains exceeding ₹1.25 lakh in a financial year (plus applicable surcharge and cess) |
| Business Income | Your trading activity is treated as a business—for example, intraday trading or frequent/systematic trading activities. | According to your applicable income-tax slab rate |
 5 mins