Return on Assets (ROA): Formula, Example, Calculator, DuPont Analysis, Industry Benchmarks

 Author
 Editor
Return on Assets (ROA) is a profitability ratio used in fundamental analysis to calculate how efficiently a company is using its assets to generate profit. ROA is typically expressed as a percentage to make it easy for you to analyse and compare the asset utilization of a company.
In this blog, you will learn to calculate ROA step by step using real world examples. You will also get a ROA calculator to calculate ROA instantly, break down ROA with DuPont analysis to uncover the drivers behind the number, and compare ROA benchmarks across industries to see how a company stacks up against its peers.
What is Return on Assets?
Return on Assets is a financial metrics or financial ratio used in fundamental analysis to find out how efficiently a company is using its assets to generate profit. This ratio is expressed as a percentage, where ROA 5% or higher is often considered good for many industries, while ROA 10% or higher is considered excellent.
Why is ROA Important to Investors?
ROA is important to investors because it tells about 5 major fundamental insights about any company, which includes measuring management efficiency, comparing companies, identifies-capital efficient businesses, evaluating long-term profitability, and helps detect operational problems.
- Measures Management Efficiency: ROA percentage tells how efficiently a company is using its assets to generate net income. Companies with a ROA percentage higher than 5% are generally considered better for investing.
- Helps Compare Companies: Investors also use ROA ratio to compare companies within the same industry, which allows them to filter highly efficient companies from the competitors. A company with higher ROA is generally preferred by investors as it gives the company a competitive advantage.
- Identifies Capital-Efficient Businesses: Some companies need billions of dollars in factories, equipment, and inventory to earn profits, while others generate similar earnings with far fewer assets. A consistently high ROA often signals a capital-efficient business that can grow without requiring large investments.
- Evaluates Long-Term Profitability: If a company has a stable or improving ROA over a several years, it indicates a strong fundamentals and disciplined management.
- Helps Detect Operational Problems: Declining ROA over a several years indicates inefficient use of assets, poor capital allocation, or excessive investment in unproductive assets.
However, we do not discard stock immediately just because its ROA is low. We first try to look into the reasons behind the low RAO by combining ROE, ROIC, profit margins, or debt-to-equity ratio to get a more complete view of the company’s financial health.
Return on Assets Formula
The standard formula of ROA that measures the company’s efficiency to use its assets to generate profit is given below.
ROA = Net Income ÷ Average Total Assets × 100
Where,
- Net Income: Profit left after deducting all operating expenses, interest, and taxes
- Beginning Total Assets: The total asset company owns at the starting of the reporting period.
- Ending Total Assets: The total assets the company owned at the end of the reporting period.
- Average Total Assets: The average value of assets used during the reporting period.
The average total asset can be calculated using the formula given below.
Average Total Assets = (Beginning Total Assets + Ending Total Assets) ÷ 2
We usually use average assets because it provides a more accurate measure because a company’s assets can increase or decrease throughout the year.
However, there is one more formula, a simplified ROA formula to calculate ROA which uses
ROA = Net Income ÷ Ending Total Assets × 100
This simplified formula is often used for quick analysis, but it is less accurate than using average total assets.
How to Calculate ROA Step by Step
You can calculate ROA for any company by following six major steps. The steps include finding net income, finding beginning total asset, finding ending total asset, calculating average total asset, dividing net income from average total asset, and then multiplying the result with 100.
- Step 1 (Find Net Income): It is profit left after deducting all operating expenses, interest, and taxes. You can locate net income in the last line of the income statement of the business.
- Step 2 (Find Beginning Total Assets): Open the previous year balance sheet and note the total assets. This will mark the company’s assets at the beginning of the reporting period.
- Step 3 (Find Ending Total Assets): Now open the current year balance sheet and note the total assets. This will mark the company’s assets at the end of the reporting period.
- Step 4 (Calculate Average Total Assets): After getting beginning total assets and ending total assets, calculate average total asset by adding both the numbers and dividing it by 2. This represents the average assets used during the year.
- Step 5 (Divide Net Income by Average Total Assets): By dividing the net income with average total asset, you will get a company’s return on assets over a selected time period. However, it will be in the form of a decimal number.
- Step 6 (Multiply by 100): To express the ROA as a percentage, multiply the result by 100.
By following the above six steps, you can calculate and compare the ROA of any given company.
Example of ROA Calculation
Let’s calculate the ROA for Tata Steel Ltd for FY26. First we will look at the net profit for Tata Steel Ltd in FY26 using the Strike Money platform.
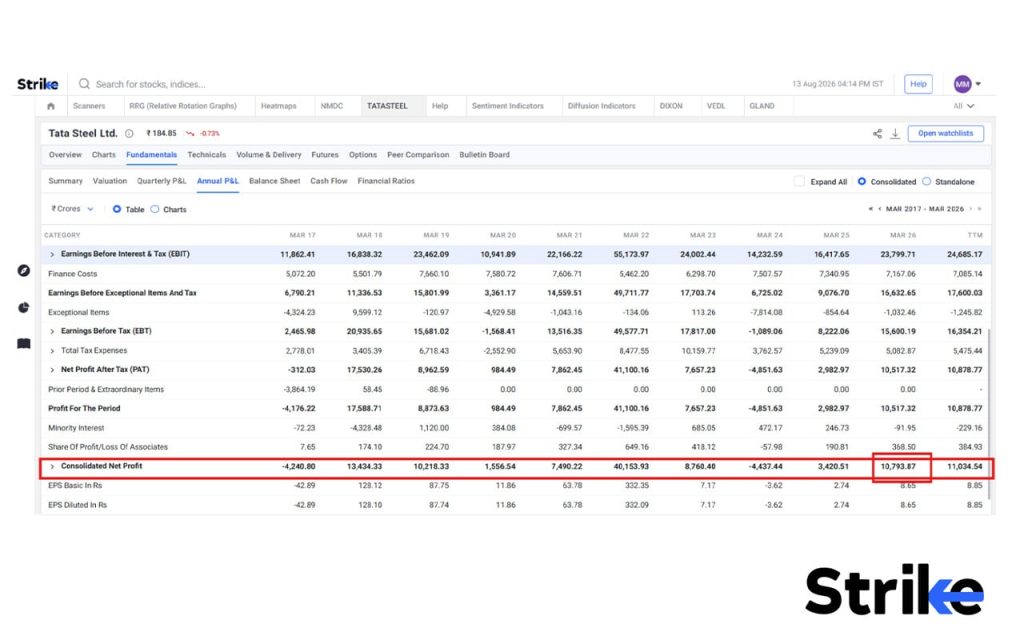
The consolidated net profit of Tata Steel Ltd for FY26 is ₹10,793.87 crore. Let’s now get the average total asset of Tata Steel Ltd. To calculate the total average asset, we will need a total beginning asset and a total ending asset.
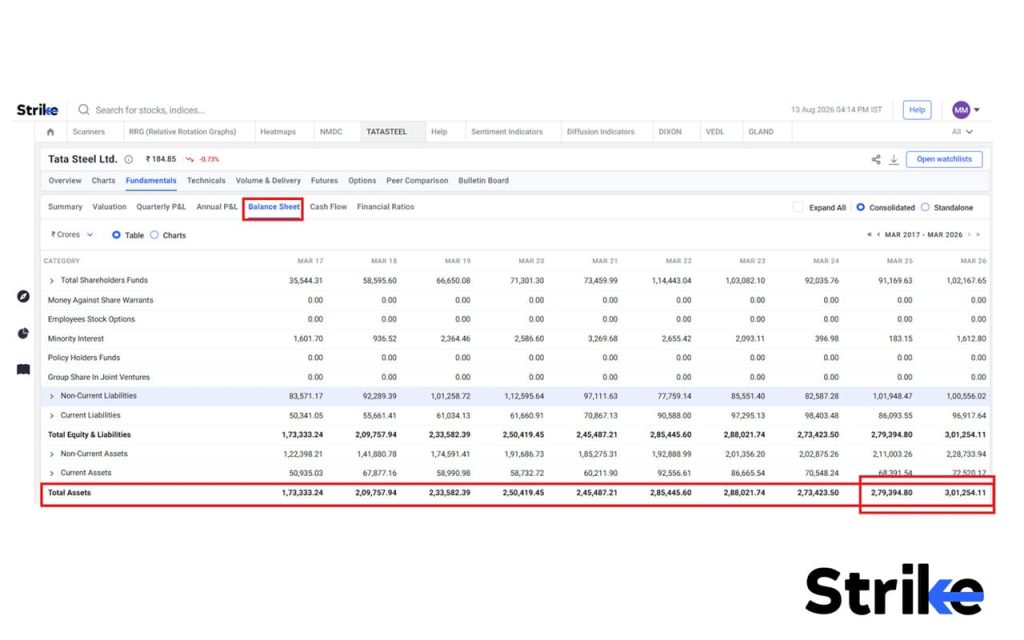
As we can see in the balance sheet of the company, the total beginning asset for Tata Steel Ltd is ₹2,79,394.80 crore and the total ending asset for Tata Steel Ltd is ₹3,01,254.11 crore.
| Particulars | Value |
| Net Income | ₹10,793.87 crore |
| Beginning Total Assets | ₹2,79,394.80 crore |
| Ending Total Assets | ₹3,01,254.11 |
First we will calculate the average total asset by combining beginning total asset and ending total asset and dividing it by 2.
- Average Total Assets = (Beginning Total Assets + Ending Total Assets) ÷ 2
- Average Total Assets = (₹2,79,394.80 + ₹3,01,254.11) ÷ 2
- Average Total Assets = ₹2,90,324.46 crore
Now, we will calculate the ROA using the ROA formula.
- ROA = (Net Income ÷ Average Total Assets) × 100
- ROA = ₹10,793.87 ÷ ₹2,90,324.46 × 100
- ROA = 3.72%
An 3.72% % ROA means that Tata Steel Ltd generated a profit of ₹3.72 for every ₹100 invested in assets during the financial year.
Download ROA Calculator
By using this ROA calculator, you can quickly be able to calculate the ROA of any company. Just put the value of Net profit and a total asset.
How Does the DuPont Analysis Explain ROA?
The dupont analysis helps you understand why a company’s ROA is what it is, instead of telling you what a company’s ROA is. Which means, instead of saying the company’s ROA is 4%, it tells you why is the ROA 4%?
Dupont analysis breaks ROA into two simple parts, profit margin and asset turnover.
ROA = Net Profit Margin × Asset Turnover
Which you can expand to
ROA = (Net Income ÷ Revenue) × (Revenue ÷ Average Total Assets)
- Profit Margin: It tells you how much profit a company keeps from every ₹100 of sales. A higher profit margin means the company earns more profit from each sale.
- Asset Turnover: This tells you how efficiently a company is using its assets to generate sales. Higher asset turnover means the company generates more sales from its assets.
Suppose a company has net profit of 8% and asset turnover of 0.5X, then according to DuPont Analysis the ROA will be calculated as follows.
ROA = Net Profit Margin × Asset Turnover
ROA = 8% × 0.5 = 4%
This method will help you compare the ROA of two companies, because two companies can have the same ROA but can achieve it differently.
What Assets Are Included in ROA?
ROA uses total assets in its calculation which includes both current assets and non current assets.
1.Current assets: An asset that can be converted into case or can be used within one year usually comes into current assets. Such assets are briefly discussed below in the table.
| Current Asset | What It Includes |
| Cash & Cash Equivalents | Cash in hand, bank balances, and short-term deposits. |
| Accounts Receivable | Money customers owe the company for goods or services sold on credit. |
| Inventory | Raw materials, work-in-progress, and finished goods available for sale. |
| Short-Term Investments | Investments expected to be sold or mature within one year, such as treasury bills or money market instruments. |
| Other Current Assets | Prepaid expenses, advances, and other assets expected to be used or converted into cash within one year. |
2. Non-Current Assets: An asset that helps businesses generate revenue over many years. Such assets are briefly discussed below in the table.
| Non-Current Asset | What It Includes |
| Property, Plant & Equipment (PP&E) | Land, buildings, factories, machinery, vehicles, and equipment used in business operations. |
| Right-of-Use (ROU) Assets | Assets leased by the company, such as offices, warehouses, or equipment, recognized under lease accounting standards. |
| Intangible Assets | Patents, trademarks, software, licenses, copyrights, and other non-physical assets. |
| Goodwill | Premium paid over the fair value of assets when acquiring another business. |
| Long-Term Financial Investments | Investments in shares, bonds, subsidiaries, or joint ventures held for more than one year. |
| Deferred Tax Assets | Future tax benefits the company expects to realize, such as tax loss carryforwards. |
| Other Non-Current Assets | Long-term security deposits, capital work-in-progress, and other assets expected to provide benefits beyond one year. |
However, it is not necessary to use all the assets to calculate ROA, because many professionals usually exclude assets which do not contribute to the core operations of the company. Such assets are Excess Cash, Non-Operating Investments, Discontinued Operation Assets, and Goodwill.
How Do You Interpret Return on Assets?
Based on varying profitability, an ROA can be interpreted as positive ROA, negative, ROA, rising ROA, falling ROA, and stable ROA.
- ROA Positive: Company is profitable, where assets are generating income
- ROA Negative: Company is loss-making where a persistent negative ROA is a warning sign
- Increasing ROA: It means that the Profit is growing faster than assets, signalling improving efficiency.
- Decreasing ROA: Profitability or asset efficiency is declining
- ROA is Stable: Consistent asset efficiency over time
Make sure you don’t make any decision based on current ROA value. Look for the ROA trend over time for a meaningful analysis. You can also consider comparing the ROA of your selected from its industry peers and their trends.
What Is a Good Return on Assets?
There is no specific number to decide what is a good return on assets. Whether the ROA is good or not entirely depends on the industry that you are analyzing. For different industries, a good ROA percentage differs.
For an asset heavy industry like utilities, airlines, manufacturing, telecom, or real estate, where they need a massive capital investment, a ROA of 5% is considered to be good. Whereas, for asset light industries like software, consulting, or professional services, where they don’t need any heavy physical infrastructure, a ROA percentage ranging from 15–20% is considered good.
Therefore, to find out whether the ROA is actually good, look for the following three points instead of just looking at the percentage.
- Compare the company with the other related companies in the same industry.
- Compare the ROA of a company with its own historical ROA.
- Compare against the industry average.
The table below mentions the typical ROA percentage range for different sectors.
| Sector Type | Typical “Good” ROA |
| Technology / Software | 15%–25%+ |
| Consumer Goods | 8%–15% |
| Retail | 5%–10% |
| Manufacturing | 3%–7% |
| Utilities | 2%–5% |
| Banks | 1%–1.5% |
In the field of fundamental analysis, an ROA above 5% is generally considered good for most non-financial companies, where 20% or above is even better. This is why practitioners of fundamental analysis first compare a company’s ROA with its industry peers and then evaluate whether it has consistently stayed above the industry average over several years.
Why Does ROA Differ Across Industries?
Return on Assets (ROA) differs across different industries because every business needs different levels of assets and follows a different business model to generate profits. There are four major reasons why ROA differs across industries and these reasons are briefly discussed below.
- Different Capital Requirements: Some businesses would need heavy factories, machinery, or infrastructure, while others require very few physical assets. Such asset heavy industries usually have a lower ROA than asset-light industries.
- Different Profit Margins: Industries that have high-margin businesses, retain more profit from each sale, resulting in a higher net profit and higher ROA. Whereas, low-margin businesses generally have lower ROAs.
- Different Asset Turnover: Companies that are quick to generate revenue from their assets tend to have higher ROAs than businesses whose assets take years to produce returns.
- Different Accounting Practices: Depreciation methods, intangible assets, goodwill, and large cash balances can affect the value of total assets, causing ROA to vary even between similar companies.
As ROA differs from one industry to another because of the above mentioned factors, ROA should always be compared with companies in the same industry rather than across different sectors.
ROA Analysis for Banks and Financial Institutions
For banks and financial institutes, ROA works little differently because their business model is different from the other industries. If you would have seen, banks and financial institutions typically have 1–2% ROA, which is actually considered to be good.
The reason is, unlike non-financial industries, where assets include equipment, inventory, or property, assets for banks and financial institutions are loans it has issued and the securities it holds. Therefore, the total assets shown on the balance sheet of a bank and financial institutes are comparatively very large.
However, investors also analyse ROE along with ROA in the case of banks and financial institutions because banks use a lot of borrowed money (customer deposits) to earn profits. As a result, a bank can report a high ROE simply by using more leverage, even if its ROA remains low. By comparing both ratios, investors can determine whether the bank’s returns come from efficient operations or from taking on higher financial risk through excessive leverage.
- Bank A: ROA = 1.2%, ROE = 12%
- Bank B: ROA = 0.8%, ROE = 20%
Although Bank B has a higher ROE, its lower ROA suggests it may be using more leverage to increase shareholder returns. If loan defaults rise or economic conditions worsen, this higher leverage can make the bank riskier.
How to Compare ROA Between Two Companies
We compare ROA between two companies to identify which company is using their assets more efficiently to generate net profit. However, for a fair ROA comparison there are 6 points you should check.
- Compare Companies in the Same Industry: Always compare companies that operate in the same industry or sub-sector, because different industries have different ROA percentage.
- Compare Similar Companies: Select the companies with similar size, business model, and growth stage. Choose companies with a similar size, business model, and growth stage.
- Look at the ROA Trend: Look for the last 3-5 years of ROA trend instead of relying on one year ROA. A rising ROA indicates improving efficiency, stable ROA indicates consistent performance, whereas falling ROA indicates weakening profitability.
- Check for One-Time Events: A one-time big event like large asset sales, tax benefits, or exceptional gains/losses can temporarily affect ROA. Try to normalize earnings whenever possible.
- Compare ROE Alongside ROA: Check ROE in case both companies have the same ROA. If one company had a higher ROE, it means, it may be using more debt to increase shareholder returns.
- Consider Accounting Differences: Different depreciation methods, asset valuations, or treatment of intangible assets can affect ROA. Keep these differences in mind, especially when comparing companies from different countries.
Apart from these points we also look at whether the companies where ROA is improving alongside operating margins. When both metrics rise together, it usually indicates genuine improvements in business efficiency rather than accounting adjustments or one-time gains.
Can a Company’s ROA Be Too High?
Yes, companies’ ROA can be too high, and like we discussed, high ROA is usually considered good. However, too high ROA is not always good. Sometimes high ROA is caused by some other factors instead of better business. That’s why it is very important for investors to distinguish between a good high ROA and high ROA due to other factors.
There are three major scenarios when a company’s ROA can be too high. These scenarios are briefly discussed below.
- Underinvestment keeps assets low, boosting ROA temporarily but limiting future growth.
- One-time asset sales inflate profits and make ROA appear unusually high.
- Older, depreciated assets reduce the asset base, raising ROA without operational improvement.
A high ROA is generally desirable, but an extremely high ROA should be investigated. Check whether it is driven by efficient operations, one-time gains, older depreciated assets, or underinvestment. Always compare ROA with industry peers and analyze its trend over several years before drawing conclusions.
What Does Negative ROA Mean?
A negative Return on Assets (ROA) means that the company is not able to generate enough profit from its assets to cover the expenses. There are five major reasons why a company posts a negative ROA.
- Operating losses: Core business expenses are (salaries, rent, raw materials, marketing) exceeding revenue during that period.
- One-time impairments or write-offs: A large non-cash charge such as writing down goodwill, inventory, or an underperforming acquisition can push net income negative even if day-to-day operations are healthy.
- Restructuring or severance costs: Layoffs, plant closures, or legal settlements create one-time charges that temporarily distort profitability.
- High interest expense: Heavily leveraged companies can see interest payments erode net income to the point of a loss, even with positive operating profit.
- Early-stage or heavy reinvestment phase: Startups and growth-stage companies often run at a deliberate loss while investing in R&D, infrastructure, or market share before revenue catches up.
However, do not immediately remark negative ROA as a red flag. Context determines whether a negative ROA is a red flag or simply a phase of the business cycle.
Should ROA Use Net Income, EBIT or NOPAT?
Generally ROA uses net income in its calculation, but practically analysts also use EBIT or NOPAT depending on what they want to analyze.
Let’s discuss the scenarios where you can consider using EBIT or NOPAT.
- ROA Using Net Income: It is the most common way of calculating ROA because it includes all expenses, including operating costs, interest, and taxes. You can use net income cost to calculate ROA when you are evaluating a company’s overall profitability, analyzing a company from an investor’s perspective, or want to compare the reported ROA of listed companies.
- ROA Using EBIT: When analysts want to analyze the companies based on operation performance, they usually use EBIT instead of net profit to calculate ROA. EBIT excludes interest expense and income taxes, helping analysts focus more on operating performance.
- ROA Using NOPAT: NOPAT (Net Operating Profit After Tax) measures operating profit after taxes but before interest. This removes the impact of financing decisions while still considering taxes. This gives a clearer picture of how efficiently the company’s operations generate profits. You can use NOPAT in ROA calculation when comparing companies with different capital structures, measuring long-term operating efficiency, or performing advanced valuation or financial analysis.
Therefore, there is no single “correct” profit measure for every ROA analysis. Net income is best for overall shareholder profitability, while EBIT or NOPAT is more useful when you want to evaluate operating efficiency without the effects of financing decisions.
Can You Calculate ROA Using Ending Assets?
Yes, you can calculate the ROA using ending assets, but it is not a preferred method to follow. Analysts mostly use average total assets instead of ending assets because a company’s assets can change throughout the year due to acquisitions, asset sales, capital expenditure, or business expansion. ROA measures how efficiently a company used its assets during the entire period, not just at the end of the year.
However, use of ending assets is acceptable during these three scenarios.
- Beginning asset data is unavailable.
- You are performing a quick analysis.
- The company’s asset base did not change significantly during the year.
In these cases, the difference between using average and ending assets is usually small.
How to Calculate Quarterly and Trailing-Twelve-Month ROA
ROA for quarter or for trailing-twelve months can be calculated by using the basic ROA formula itself. The main difference occurs is the period of net income used in the calculation.
For quarterly ROA calculation we will use quarterly net income. So, instead of looking for an annual P&L report, look for a quarterly P&L report.
Quarterly ROA = (Quarterly Net Income ÷ Average Total Assets During the Quarter) × 100
TTM ROA measures profitability over the most recent four quarters, making it more stable than quarterly ROA because it smooths out seasonal fluctuations.
TTM ROA = (TTM Net Income ÷ Average Total Assets Over the TTM Period) × 100
Use Quarterly ROA to monitor recent changes in a company’s performance, especially after new product launches, acquisitions, or economic events. Use TTM ROA when comparing companies or evaluating long-term profitability, as it provides a more reliable picture by reducing the impact of seasonal fluctuations.
| Feature | Quarterly ROA | TTM ROA |
| Time Period | One quarter | Last four quarters |
| Net Income Used | Quarterly net income | Sum of last four quarters’ net income |
| More Volatile? | Yes | No |
| Best For | Tracking recent performance | Evaluating overall profitability |
| Most Used By | Short-term investors and analysts | Long-term investors and analysts |
How Can a Company Improve Its ROA?
There are five different ways a company can improve its ROA
- Increase Profitability: A higher profitability directly improves the company’s ROA. Companies can achieve high profit through increased sales and revenue, improved profit margins, reduced operating and production costs.
- Generate More Revenue from Existing Assets: Instead of buying new assets, companies can utilize their existing assets in a better way to generate more revenue. For instance, companies can increase production using existing factories or expanding sales without opening new locations.
- Sell Unproductive Assets: Unproductive assets like unused buildings, old equipment, excess inventory, or non-core investments increase total assets without generating profits. By selling them the low asset base and can improve ROA.
- Invest in High-Return Projects: When adding new assets, companies should invest only in projects expected to generate strong returns. Disciplined capital allocation helps maintain or improve ROA over the long term.
The best way to improve this financial ratio is through genuine operational efficiency, not by simply reducing assets. Companies that consistently increase profits while making better use of existing assets tend to achieve a higher and more sustainable financial ratio, reflecting true health. Avoid companies that boost their performance metrics by underinvesting in maintenance or R&D, as this may artificially inflate the results and hurt long-term performance.
What ROA Trends Should Investors Look For?
An investor should at least analyze the ROA trend for the last 3-5 years instead of a single ROA figure, because it shows how efficiently the business is using its assets to generate profits over the period of time.
The table given below will help you to interpret the ROA trend over the period of time.
| ROA Trend | What It Indicates |
| Steady gradual rise | A positive sign. The company is consistently becoming more efficient at generating profits from its assets. |
| Sudden one-year spike | Investigate further. It could be caused by one-time gains, asset sales, or accounting adjustments rather than sustainable growth. |
| Gradual sustained decline | An early warning that profitability or asset utilization may be weakening. |
| Decline in line with the industry | May reflect economic slowdown or industry-wide challenges rather than company-specific problems. |
| Decline worse than competitors | A warning sign that the company may be losing its competitive advantage or facing operational issues. |
| Rising ROE but flat or falling ROA | Returns may be driven by higher debt (leverage) rather than better business performance. Investors should assess the company’s financial risk. |
We usually prefer companies with steadily improving ROA ratio for at least three years rather than companies reporting one unusually high ROA, because a consistent upward trend usually reflects sustainable operational improvements.
Why is ROE usually higher than ROA?
Return on Equity (ROE) is usually higher than Return on Assets (ROA) because ROE is calculated using equity only whereas ROA is calculated using the entire asset which includes debt (financial leverage) and shareholder’s own money as well.
Therefore, while calculating ROE, the denominator is small compared to ROA, where the denominator is big. Hence the ROE usually comes higher than ROA.
While comparing two companies, check ROE and ROA simultaneously. A business generating a 9% ROA with conservative debt is often financially stronger than another producing a 14% ROE but only a 3% ROA through aggressive borrowing.
Can ROA be high while ROIC is low?
Yes, ROA can get higher compared to a ROIC, but it is not very common, because ROIC’s denominator is usually smaller because we use invested capital, whereas, the ROA’s denominator is usually higher as we use total assets. This means, normally a ROIC ratio should be higher than ROA.
There are two major scenarios where ROA can be higher while the ROIC is low.
- The Company Has a Large Amount of Invested Capital: A company may have invested heavily in new factories, equipment, or acquisitions. If these investments have not yet started generating strong profits, ROIC can remain low, even if ROA is relatively high.
- High Non-Operating Assets: A company may generate good profits from its assets, resulting in a high ROA. However, if it has invested a large amount of long-term capital that is not producing adequate returns, its ROIC will be lower.
Although it does not happen very often, when it does it simply means that the company has recently made large investments that haven’t started paying off yet, or a capital is not being allocated efficiently, or some long-term investments are generating weak returns.
Is ROA a type of ROI?
Yes, in a broader sense, ROA is a specific variation of ROI because they both measure how much profit is generated from the investment, but they measure different types of investments.
- ROI (Return On Investment): It is a broader and flexible concept that is used to measure return of any kind of specific investment, such as a project, property, or marketing campaign.
- ROA (Return On Asset): It measures the return generated specifically on a company’s assets such as cash, buildings, machinery, inventory, and equipment.
| Aspect | ROI (general) | ROA (specific) |
| Scope | Any investment (a stock, a project, a campaign, a whole company) | Specifically a company’s total assets |
| Denominator | Cost or amount invested (varies by context) | Total assets on the balance sheet |
| Numerator | Gain or profit from that specific investment | Company-wide net income |
| Standardization | No fixed formula — varies by use case | Standardized formula, consistently reported in financial statements |
| Use case | Evaluating a single decision or investment | Evaluating overall company efficiency in using its assets |
Can ROCE be high when ROA is low?
Yes, a company can have a high ROCE even though the ROA is low, which is inherently not a red flag. This gap usually occurs because both of these ratios measure different things and use different domains.
ROA uses all the assets of the company in its calculation, including those funded by short-term/current liabilities (like accounts payable, short-term loans, accrued expenses), that’s why the ROA ratio usually comes out lower. Whereas, ROCE excludes current liabilities from the denominator, and only focuses on the capital that’s more permanently invested in the business, which includes equity and long-term debt, that’s why the ROCE ratio comes out higher .
So if you find a company with a higher ROCE but lower ROA, it means that the business is using lots of short-term financing or debt whose interest is lowering down the net income.
 5 mins