What Is a Balance Sheet? Anatomy, Comparative Metrics, Reading Guide & Tools for Fundamental Investors
 Author
 Editor
Balance sheet is one of the main financial statements used in the world of investing to understand the financial position of the company. Balance sheet marks its origin to early forms of double-entry bookkeeping, which developed in Europe during the 15th century.
As legendary investor Peter Lynch said “If you can’t understand the balance sheet, you probably shouldn’t own it.” Therefore a balance sheet is more than just an accounting statement for investors.
By comparing balance sheet figures over the period of time, investors can interpret the financial position of the company. Therefore, a balance sheet becomes an essential starting point for evaluating the financial health and underlying strength of a business.
What is a Balance Sheet?
A balance sheet is a financial statement that shows the financial condition of the company at a specific point in time. It tells you what the company owns (assets), what it owes (liabilities), and the amount belonging to shareholders (equity).
The balance sheet works on a simple equation.
Assets = Liabilities + Equity
Since, both sides of this equation must always balance according to the basic accounting equation, it is known as the balance sheet.
What does the Balance Sheet of a Company Reveals?
The balance sheet of the company tells you what the company owns (assets), what it owes (liabilities), and the amount belonging to shareholders (equity). If these data are interpreted correctly, you will get the full story about financial health, strategy, and risk associated with the company.
What are the Main Components of a Balance Sheet?
There are three main components of the balance sheet. The components are assets, liabilities, and shareholders’ equity. Let’s discuss each of these components in detail.
1. Assets
Assets are the resources a company owns or controls that holds economic value. These resources are expected to provide future economic benefits to the company such as generating revenue, reducing costs, or supporting business operations.
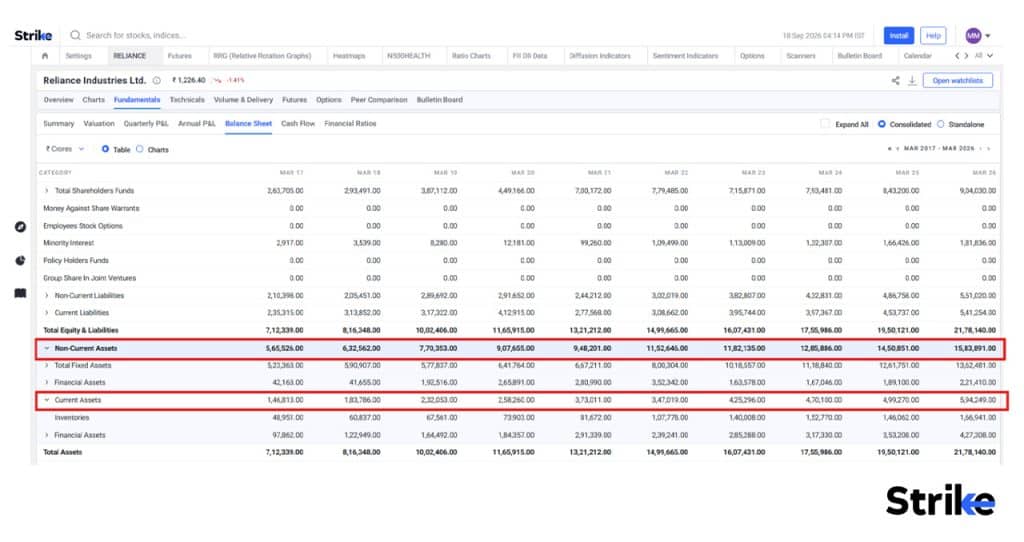
Assets are generally divided into Short term assets/ Current assets and Long term assets/ Non-current assets.
Short term assets/ Current assets
Current assets are short term assets which are converted into cash or used up within its normal operating cycle or within 12 months, whichever is longer. Following are the examples of current assets.
- Cash and cash equivalents: Cash available to the company and highly liquid short-term investments.
- Accounts receivable: Money owed to the company by customers for goods or services sold on credit.
- Inventory: Raw materials, work-in-progress, and finished goods held for sale.
- Prepaid expenses: Expenses paid in advance for goods or services that will be received in the future.
- Marketable securities: Short-term investments that can generally be converted into cash relatively easily.
Long term assets/ Non-current assets
Non current assets are long term assets which are held for more than 12 months to be converted into cash. Following are the examples of non current assets.
- Property, Plant and Equipment (PP&E): Physical assets such as buildings, machinery, equipment, and vehicles used in business operations.
- Patents: Legal rights protecting an invention.
- Trademarks: Protected names, symbols, or logos associated with a company’s products or services.
- Goodwill: An intangible asset generally created when one company acquires another for more than the fair value of its identifiable net assets.
- Other intangible assets: Non-physical assets such as certain brands, copyrights, licences, and intellectual property.
2. Liabilities
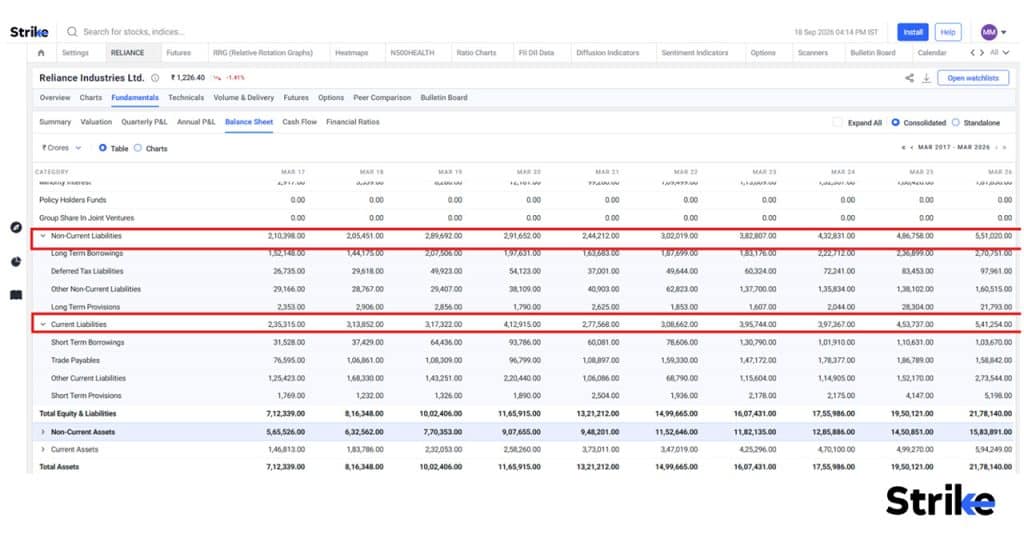
Liabilities are the financial obligations that a company owes to other parties, such as loans, tax, etc. Liabilities are generally divided into Short term liabilities/ Current liabilities and Long term liabilities/ Non-current liabilities.
Short term liabilities/ Current liabilities
Current liabilities or short-term liabilities are obligations that a company expects to pay or settle within its normal operating cycle or within 12 months, whichever is longer. Following are the examples of current liabilities.
- Accounts payable: Money owed to suppliers for goods or services purchased on credit.
- Current debt: Borrowings that are due within the short term.
- Current portion of long-term debt: The part of long-term borrowing that must be repaid within the next 12 months.
- Accrued payroll expenses: Employee salaries, wages, and related costs that have been incurred but not yet paid.
- Accrued rent and utility expenses: Rent, electricity, and other operating expenses incurred but not yet paid.
Long term liabilities/ Non-current liabilities.
Non current liabilities or long term liabilities are obligations that are generally due after 12 months. Following are the examples of non current liabilities.
- Bonds payable: Amounts the company must repay to bondholders.
- Long-term debt: Borrowings with repayment periods extending beyond 12 months.
- Lease liabilities: Future payments owed under applicable lease agreements.
- Deferred tax liabilities: Tax amounts recognised for accounting purposes that are expected to be paid in future periods.
3. Shareholders’ Equity
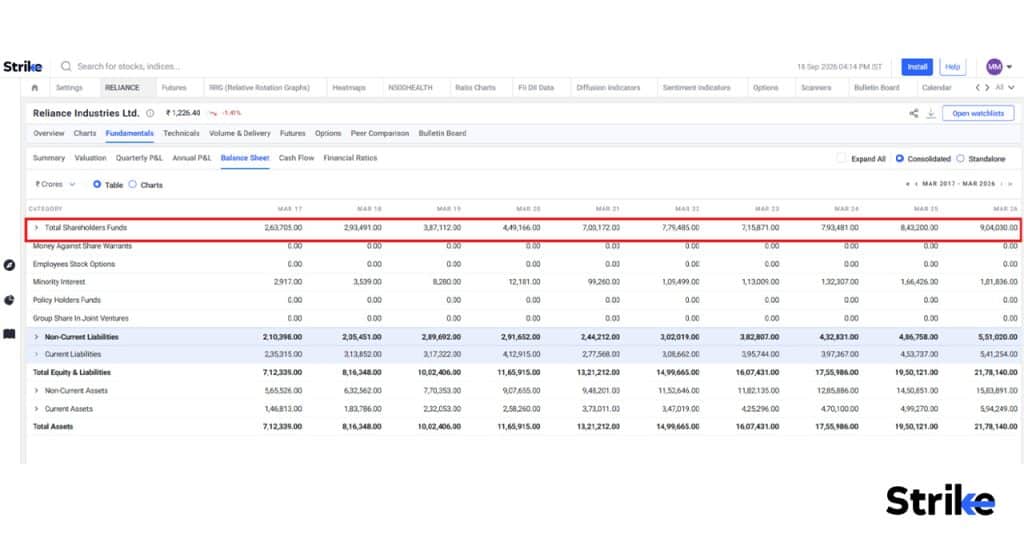
Shareholders’ equity represents a portion of the company’s assets that belongs to shareholders after deducting all its liabilities from its assets. This includes share capital and retained earnings.
- Share capital: Money raised by the company by issuing shares to shareholders.
- Retained earnings: Cumulative profits retained in the business after accounting for dividends and other applicable adjustments.
How to Get the Balance Sheet of a Company?
There are different official sources that you can use to get the company’s balance sheet, such as the company’s official website, stock exchange websites like the NSE or BSE, MCA (Ministry of Corporate Affairs) portal, or use financial data platforms like Strike Money.
- Strike Money: You can get the balance sheet of the company under the fundamental section of the stocks page.
- Company’s Official Website: Go to Investor Relations and then Financials / Annual Reports. The balance sheet is usually included in the annual report.
- NSE: Go to Corporate Filings, then Annual Reports or Corporate Filings, then Financial Results and search for the company.
- BSE: Go to Corporate Filings, then Financial Results / Annual Reports and search for the company.
- MCA: Go to MCA Portal, then View Public Documents, search for the company, and access its filed financial statements.
You can get a balance sheet from all the methods mentioned above, but I would personally suggest using analytical softwares like strike money for easy access and interpretation of the balance sheet.
How to Read a Balance Sheet?
There are four core steps to read a balance sheet which involves understanding major items, calculating key ratios, comparing the ratios and interpreting the results. Let’s learn how to read the balance sheet using Reliance Industries balance sheet.
Step 1: Understanding major items
Major items include assets, liabilities and equity share holdings. Always start with analysing assets (what company owns).
Assets
Always start with analysing assets (what company owns). This will help you understand where the company’s money is invested and how easily it can be converted into cash.
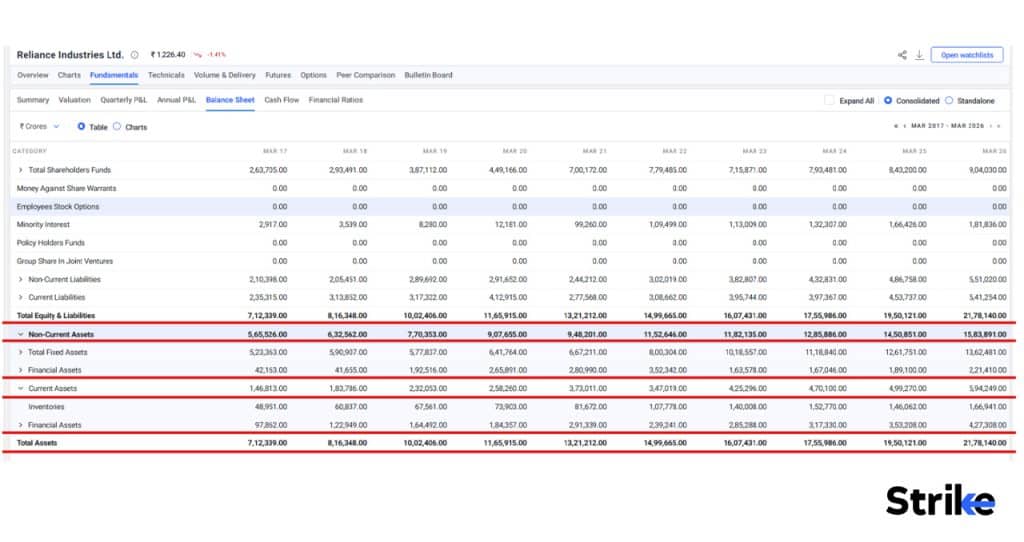
- Fixed Assets: Shows investment in property, plants and equipment.
- Investments: Shows money invested in other assets or businesses.
- Inventory: Goods held for sale or production.
- Trade Receivables: Money customers owe the company.
- Cash & Cash Equivalents: Cash readily available to the company.
For example, in the March 2026 Reliance Industries balance sheet, total assets stood at ₹21,78,140 crore, including ₹15,83,891 crore of non-current assets and ₹5,94,249 crore of current assets.
Liabilities and Equity
Next, focus on liabilities and equity to understand how these assets are financed, how much is debt and how much is shareholders’ funds. Focus mainly on three things; borrowings, trade payables, and shareholders’ funds.
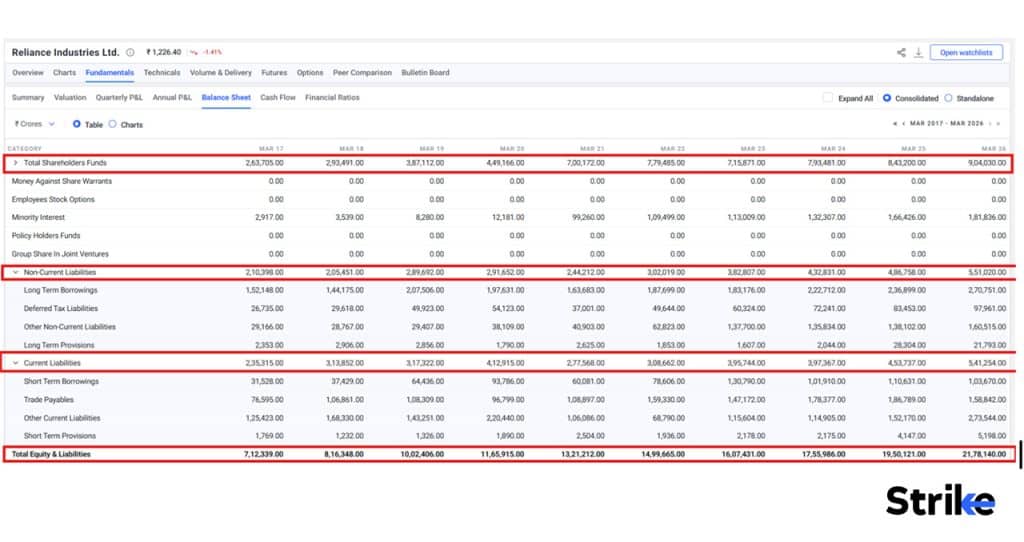
- Borrowings: Money borrowed by the company.
- Trade Payables: Money owed to suppliers.
- Shareholders’ Funds: Capital and accumulated reserves belonging to shareholders.
In our Reliance balance sheet in March 2026 following are the liabilities.
- Long-term borrowings = ₹2,70,751 crore
- Short-term borrowings = ₹1,03,670 crore
- Shareholders’ funds = ₹9,04,030 crore
This figure gives us a basic figure of what Reliance Industries owns and how those assets are financed. However, this data is not enough to make any investing decisions. o get deeper insights, the next step is to calculate and compare key balance-sheet ratios, such as the current ratio, debt-to-equity ratio, and asset turnover ratio.
Step 2: Calculate Key Ratios
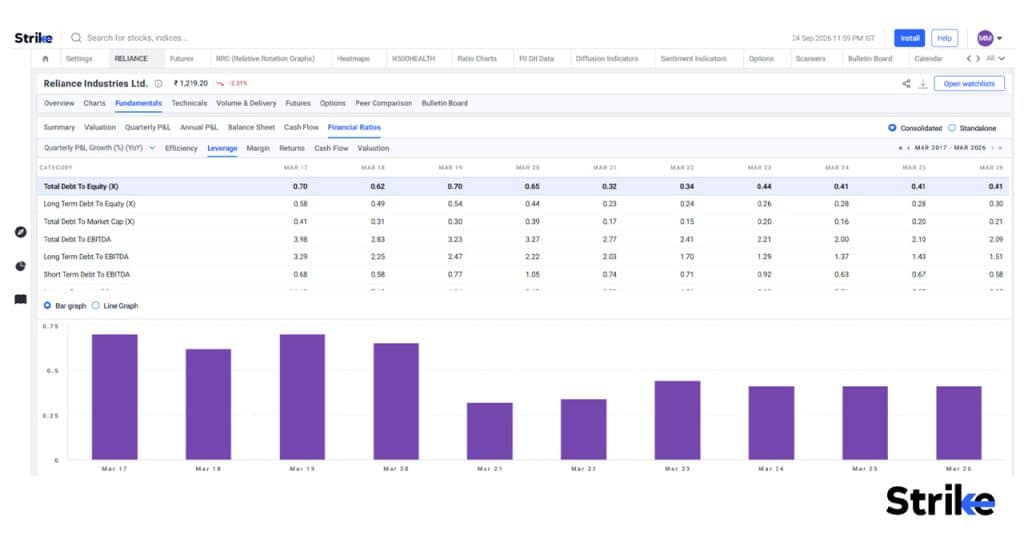
Once you understand the major items, use ratios such as debt-to-equity, current ratio, and quick ratio to analyse the company’s financial position. You can analyse these ratios manually using data from the balance sheet, or else use ready-made calculated ratios available on analytical softwares.
Step 3: Compare and Interpret
The final step is to compare these ratios with previous years, competitors,and industry averages rather than looking at them in isolation.
- Previous years: Is the company’s financial position improving or deteriorating?
- Competitors: How does its financial structure compare with similar companies?
- Industry averages: Is the ratio typical for the industry?
For example, a Debt-to-Equity ratio of 0.41 becomes more meaningful when you check whether it was 0.25 or 0.60 in previous years.
What Does Comparative Balance Sheet Reveal about a Company?
Comparative balance sheet means a balance sheet that compares the assets, liabilities, and shareholders’ equity of a given company for two or more years side by side. This reveals how the company’s position has changed over time, helping investors to interpret the data more precisely.
Given below is the screenshot of the 10 year period comparative balance sheet of Torrent Pharma stock.
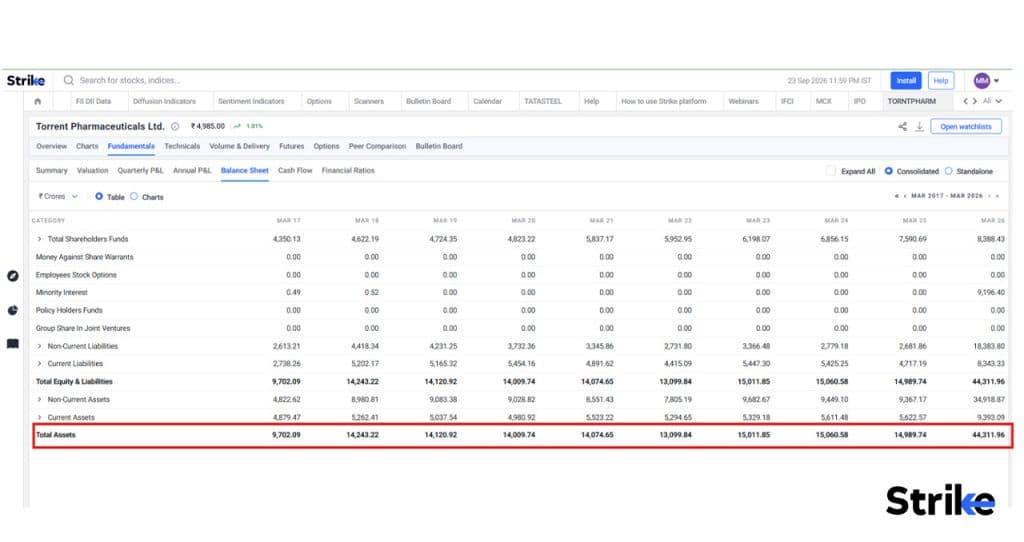
We can easily compare how the total assets of Torrent Pharma stock have increased from ₹9,702 crore in March 2017 to ₹44,312 crore in March 2026, indicating a significant expansion in the company’s asset base. At the same time, shareholders’ funds have also increased from ₹4,350 crore to ₹8,388 crore, showing growth in the company’s net worth.
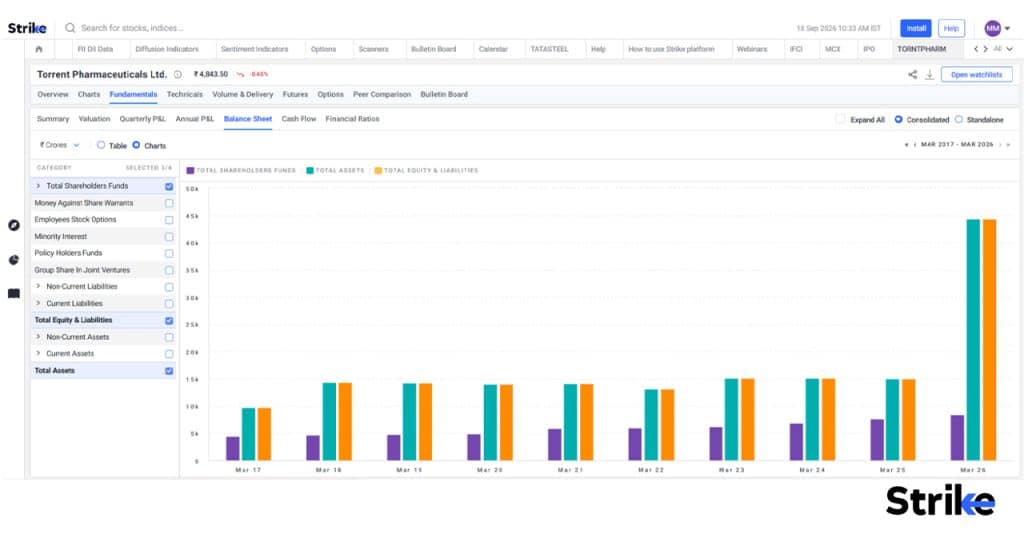
In Strike Money platform, you also get the option to track and compare the balance sheet data using charts, making it easier to visualise trends and understand how the company’s financial position has changed over time.
Piotroski F-Score: A 9-Point Framework for Evaluating Financial Strength
The Piotroski F-Score is a 9-point scoring system developed by accounting professor Joseph Piotroski to evaluate a company’s financial strength. These nine signals are grouped into three categories
| Category | What It Evaluates |
|---|---|
| Profitability | Positive net income, positive operating cash flow, improving ROA, and quality of earnings |
| Leverage, Liquidity & Source of Funds | Lower leverage, improving liquidity, and no new shares issued |
| Operating Efficiency | Improving gross margin and asset turnover |
A Piotroski 9 check points to evaluate the financial strength of the company is briefly discussed below in the table.
| Piotroski Criteria | What It Checks | Pass Condition | |
| 1 | Positive Net Income | Whether the company is profitable | PAT > 0 |
| 2 | Positive Operating Cash Flow | Whether core operations generate cash | OCF > 0 |
| 3 | Increasing ROA | Efficiency of assets in generating profit | Current ROA > Previous ROA |
| 4 | Quality of Earnings | Whether profits are supported by cash flow | OCF > Net Income |
| 5 | Lower Leverage | Dependence on debt | Current Debt/Assets < Previous year |
| 6 | Improving Liquidity | Ability to meet short-term obligations | Current Ratio > Previous year |
| 7 | No New Shares Issued | Whether existing shareholders face dilution | Current Shares ≤ Previous year |
| 8 | Increasing Gross Margin | Profit retained after direct costs | Current Gross Margin > Previous year |
| 9 | Increasing Asset Turnover | Efficiency in using assets to generate revenue | Current Asset Turnover > Previous year |
Each signal receives 1 point if the condition is met and 0 if it is not, giving a total score between 0 and 9.
| Piotroski F-Score | Financial Strength |
|---|---|
| 8–9 | Strong |
| 6–7 | Good |
| 4–5 | Moderate |
| 0–3 | Weak |
A higher score indicates that more of the framework’s financial-strength conditions are satisfied.
We Backtested the Piotroski F-Score on 10 NSE Stocks
To see how effective the nine-point Piotroski F-Score is, we applied the nine-point Piotroski F-Score to 10 listed stocks on NSE and compared their subsequent performance with the Nifty 50.
We started with scoring each stock from 0 to 9 based on the nine financial signals covering profitability, leverage, liquidity, and operating efficiency. Then we grouped the stocks based on their F-Scores and compared their 1-year returns and 3-year CAGR with the Nifty 50.
Here is what the exercise revealed.
| Stock | F-Score | 1-Year Return | 3-Year CAGR |
| Sun Pharma | 9 | -0.7% | 22.0% |
| Bharat Electronics | 9 | -0.7% | 50.6% |
| Torrent Pharma | 8 | +43.0% | 35.9% |
| Hindalco | 8 | +68.4% | 33.3% |
| Vedanta | 8 | -33.0% | 3.0% |
| TVS Motor | 8 | +20.9% | 35.1% |
| Britannia | 8 | -5.6% | 2.2% |
| Vodafone Idea | 7 | +80.1% | 22.1% |
| Suzlon Energy | 5–6 | -16.1% | 88.7% |
| Tata Technologies | 6 | +9.4% | N/A |
| Nifty 50 | — | -4.5% | 7.7% |
Stocks with stronger financial scores generally showed healthy long-term performance with most of the stocks outperforming Nifty 50 in this sample. However, individual stocks produced very different outcomes.
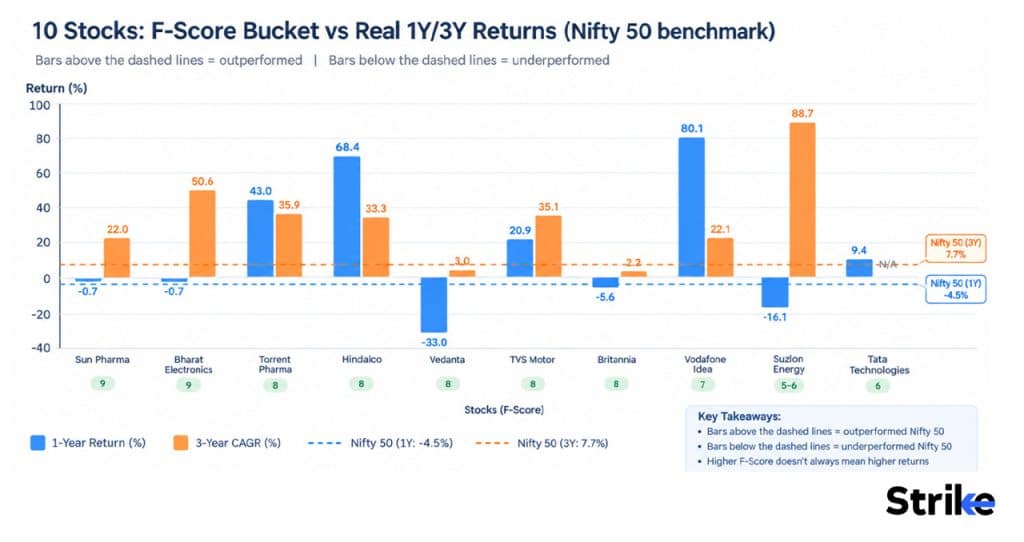
For example, Hindalco, with an F-Score of 8, gained 68.4% over one year, while Vedanta, also with an F-Score of 8, declined 33%.
At the same time, Suzlon Energy, with a lower F-Score, delivered an 88.7% 3-year CAGR. This shows why the Piotroski score should be treated as a financial-strength filter rather than a standalone stock-selection or return-prediction model.
What Tools You Need for Balance Sheet Analysis
Calculators and basic formulas are enough for manual analysis, but using tools like Strike Money, Moneycontrol, tally, etc can save time, reduce errors, and give you deeper insights faster.
- Strike Money: Allows you to analyse balance sheets of the last 10 years (comparative balance sheet) side by side on a single screen with option to switch between tabular format and chart format.
- Microsoft Excel / Google Sheets: Widely used tool to build comparative and common-size balance sheets, calculating ratios manually, and creating custom charts or trend lines.
- Moneycontrol: It offers balance sheet data, financial ratios, and year-on-year comparisons for publicly listed companies, useful for quick reference while researching stocks along with news.
- Tally / QuickBooks: This tool is commonly used by businesses and accountants to maintain records and generate balance sheets directly from bookkeeping data.
- Financial Ratio Calculators: Online or built-in calculators (many available for free) that instantly compute liquidity, solvency, and profitability ratios once you input balance sheet figures.
- Industry Reports & Benchmarking Tools: Useful to compare company’s financial ratios against industry averages, helping you judge whether its numbers are strong or weak relative to peers.
The right tools can make balance sheet analysis faster, easier, and more accurate. Combining financial data with spreadsheets, accounting software, and industry benchmarks helps you understand a company’s financial position more effectively.
Balance Sheet Format PDF & Excel
Download the balance-sheet (T-formate) balance sheet format PDF and Excel, with liabilities on the left and assets on the right.
It’s widely used by sole proprietors and partnership firms. The Excel file calculates totals automatically and checks whether your balance sheet is balanced.
Download Vertical Balance Sheet Format PDF & Excel
Download a vertical balance sheet format PDF and Excel that presents all items in a single column, with Sources of Funds at the top and Application of Funds below.
It clearly shows net current assets (working capital) and makes year-on-year comparison easy. Both files include current and previous year columns with a sample example.
Schedule 3 Balance Sheet Format PDF & Excel
Companies registered under the Companies Act, 2013 must prepare their balance sheet in the Schedule III format. This template follows Division I, for companies that don’t follow Ind AS, and includes the latest 2021 amendments.
The Excel version totals both sides automatically and flags any mismatch.
Difference between Provisional vs Projected vs Estimated Balance Sheets
Difference between provisional vs projected vs estimated balance sheets is briefly discussed below in the table.
| Basis | Provisional Balance Sheet | Projected Balance Sheet | Estimated Balance Sheet |
|---|---|---|---|
| Meaning | A preliminary balance sheet prepared before the final accounts are completed | A balance sheet showing expected future financial position | A balance sheet based on approximate or assumed figures |
| Time period | Usually for a period that has already ended | For a future period | Can be for a past, current, or future period |
| Data used | Mostly actual financial data available at the time | Assumptions about future revenue, expenses, assets and liabilities | Available data, assumptions, trends or management estimates |
| Purpose | To provide a preliminary view before finalisation | To plan and forecast future financial position | To approximate financial position when exact figures are unavailable |
| Certainty | Relatively high, but figures may still change | Depends heavily on assumptions | Generally less certain |
| Example | FY2025 accounts are closed, but audit adjustments are pending | Preparing a balance sheet for FY2027 based on expected growth | Estimating current assets and liabilities using incomplete information |
In simple terms, a provisional balance sheet reflects incomplete actual figures, a projected balance sheet looks at the future, while an estimated balance sheet uses assumptions to arrive at approximate figures.
Difference between Common Size Balance Sheet & Consolidated Balance Sheet
The difference between common size balance sheet and consolidated balance sheet is mentioned below in the table.
| Basis | Common Size Balance Sheet | Consolidated Balance Sheet |
|---|---|---|
| Meaning | Presents each balance sheet item as a percentage of a common base, usually total assets | Combines the assets, liabilities and equity of a parent company and its subsidiaries |
| Main purpose | To analyse the composition of the company’s financial position and compare companies of different sizes | To show the financial position of the entire corporate group as one economic entity |
| How it is prepared | Each item is expressed as a percentage of total assets | Financial statements of the parent and subsidiaries are combined, with intra-group transactions eliminated |
| Focus | Financial structure and proportions | Overall financial position of the business group |
| Companies covered | Usually one company’s balance sheet | Parent company and its subsidiaries |
| Example | Cash = ₹10 crore on total assets of ₹100 crore → 10% of total assets | Parent has ₹100 crore of assets and subsidiary has ₹50 crore → figures are combined, subject to consolidation adjustments |
Both serve different purposes: a common size balance sheet helps you compare financial structure, while a consolidated balance sheet helps you understand the business as a whole. Using both can give a clearer view of a company’s financial position.
What is Twin Balance Sheet Problem
Twin balance sheet problem is a term that is commonly used to describe a situation where company as well as banks both have weak balance sheets at the same time.
This problem usually appears when a company borrows money from a bank to fund their new project, but the project fails to perform and the company fails to repay the loan amount. As a result, bank’s bad loans and Non-Performing Assets (NPAs) increase, putting both company and bank in bad shape. Such situations choke investment and affect credit flow in the economy.
To address such a situation, several measures were introduced by the Indian government to recognize, resolve and recapitalize stressed assets.
- Insolvency and Bankruptcy Code (IBC), 2016: Created a formal, time-bound process to resolve corporate insolvency
- Asset Quality Review (AQR) by RBI: Forced banks to recognize hidden NPAs transparently
- Bank recapitalization: Government infused capital into public sector banks
- Bad bank / NARCL: A National Asset Reconstruction Company was set up to take over and manage large NPAs
These measures aim to clean up stressed bank and corporate balance sheets, improve the recovery of bad loans, and restore the flow of credit to productive businesses. This helps create healthier balance sheets for both borrowers and lenders.
What Is Schedule III Balance Sheet?
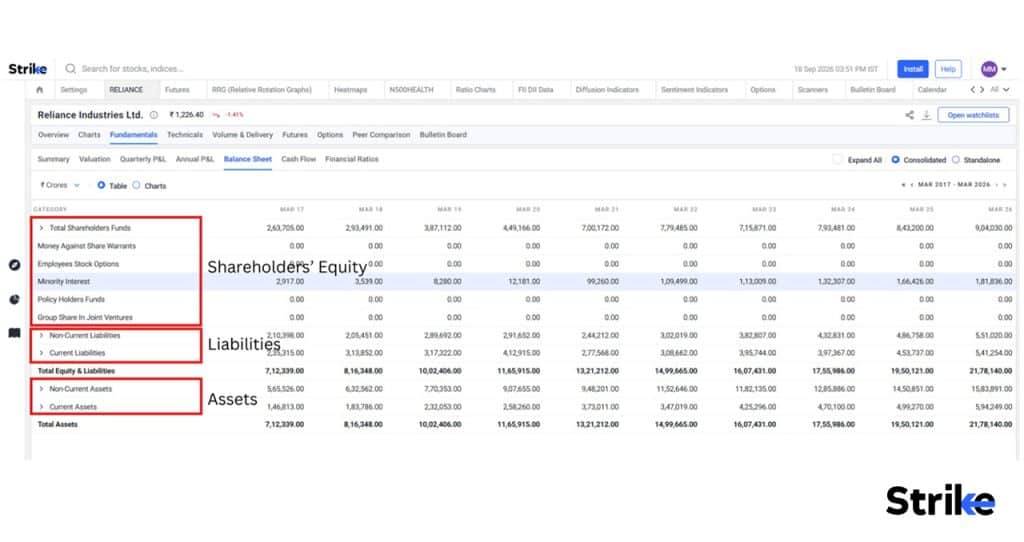
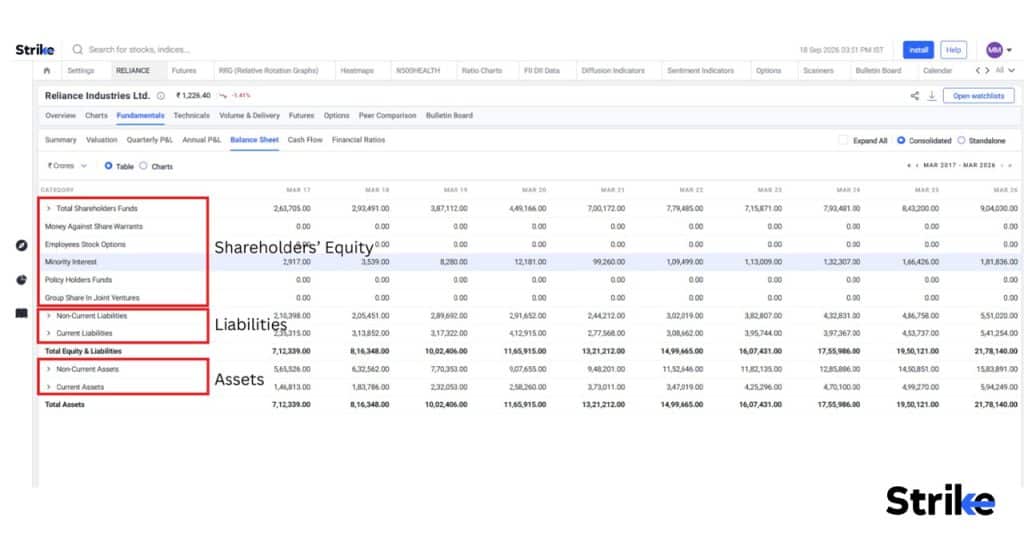
Schedule III balance sheet is a standardized format of presenting a company’s balance sheet under Schedule III of the Companies Act, 2013 (India). According to this act, a company should release their balance sheet in a similar and structured manner for easy analysis.
The format to present the balance sheet is mentioned below.
I Equity and Liabilities
- Shareholders’ Equity
- Non-current liabilities
- Current liabilities
II Assets
- Non-current assets
- Current assets
Schedule III also provides rules for classifying items as current or non-current, generally considering the company’s operating cycle and the 12-month period after the reporting date.
Below is a screen shot of the balance sheet of Reliance Industries. You can easily see the basic structure of balance sheet
Schedule III has three divisions based on different types of company and accounting frameworks.
- Division I: Companies following Accounting Standards (AS)
- Division II: Companies following Indian Accounting Standards (Ind AS)
- Division III: Certain NBFCs following Ind AS
The presentation and disclosure requirements can therefore differ depending on the type of company and accounting framework.
What are the Other Parameters You Should Look for Fundamental Analysis?
There are 10 parameters that you should check while doing fundamental analysis. These 10 parameters are briefly discussed below.
- Revenue Growth: It shows how much income a company has generated from its core business. By comparing revenue growth over several years, you can understand whether the company’s business is growing.
| Parameter | Reference / Benchmark |
|---|---|
| Revenue Growth | 10–15%+ YoY for stable businesses; 15–25%+ for high-growth companies |
| Revenue CAGR | Prefer 3–5 year CAGR over a single year to account for one-off spikes |
- Profit Growth: It involves tracking of operating profit, EBITDA, and net profit to understand whether the company is converting its revenue into profits and is it improving over time.
| Parameter | Reference / Benchmark |
|---|---|
| Profit vs Revenue Growth | Profit growth should match or exceed revenue growth; e.g., 15% revenue growth vs 5% profit growth signals margin pressure |
| Net Profit Growth | 15%+ CAGR over 3–5 years is a strong growth benchmark |
- Profit Margins: Check profit margin metrics like OPM (operating profit margin), EBITDA margin, and net profit margin to understand how much profit a company generates from its revenue.
| Parameter | Reference / Benchmark |
|---|---|
| OPM | Above 15–20% is generally healthy; varies by sector |
| Net Profit Margin | Above 10% is often considered healthy |
| Margin Trend | Should remain stable or improve over 3–5 years; declining margins warrant attention |
- Earnings Per Share (EPS): EPS measures profit on each outstanding share. By comparing EPS for multiple years, you can understand the company’s earnings growth on a per-share basis. Look for consistent EPS growth of 15%+ CAGR over 3-5 years.
- Return Ratios: Analyze return ratios like ROE (Return on Equity), ROCE (Return on Capital Employed), ROA (Return on Assets) to understand how efficiently a company uses its capital and assets.
| Parameter | Reference / Benchmark |
|---|---|
| ROE | Above 15–20% is generally strong; consistently above 20% is often preferred |
| ROCE | Above 15–20% indicates efficient use of capital |
| ROA | Above 5–7% is typically healthy; varies by industry |
- Debt and Interest Coverage: Check the company’s debt level and its ability to pay that debt by using ratios like debt-to-equity ratio, interest coverage ratio and net debt-to-EBITDA.
| Parameter | Reference / Benchmark |
|---|---|
| Debt-to-Equity Ratio | Below 0.5–1 is generally safe; below 0.3 is very conservative; above 2 is high |
| Interest Coverage Ratio | Above 4–5× suggests comfortable debt servicing; below 1.5× is a warning sign |
| Net Debt-to-EBITDA | Below 2–3× is generally manageable; above 4× may indicate higher solvency risk |
- Cash Flow: Check cash flow activity like operating cash flow, free cash flow, cash flow from investing activities, and cash flow from financing activities.
- Working Capital: Analysing working capital like inventory, trade receivables, trade payables, and working-capita are useful to understand efficiency of company’s operations.
| Parameter | Reference / Benchmark |
|---|---|
| Receivable Days | Below 45–60 days is generally healthy for most non-BFSI sectors |
| Inventory Days | Should remain stable or decline over time; a sudden increase may indicate slower sales |
| Working Capital Cycle | Shorter or negative cycles generally indicate stronger operational efficiency |
- Valuation Ratios: Check valuation ratios like P/E, P/B, etc to understan how the market is pricing the company.
| Common Valuation Ratios | |
|---|---|
| P/E | Compare with 5–10 year historical average and peers |
| P/B | Below 3–4×; banks often 1–3× |
| EV/EBITDA | Below 10–12× |
| PEG Ratio | Below 1; above 1.5–2 may indicate higher valuation |
| Dividend Yield | 1–2%+ for growth companies; 3–5%+ for mature/high-dividend sectors |
- Promoter and Institutional Holding: Promoters holding more than 50% is considered stronger as it reflects promoters confidence in his business. However, a reducing promoter holding over a period shows signs of caution.
These parameters help you look beyond a company’s share price and understand the quality and strength of its business.
 15 mins